Home Insurance
Home coverage built around your actual house.
Roof age, construction type and where you live all change the numbers. We compare real options for your address instead of handing you a one-size estimate.
Get Your Home Protected ProperlyWe compare multiple providers — not just one
We'll tell you honestly if your roof needs work before we quote
Replacement cost
Full replacement cost coverage for homes that deserve it.
Protection built around what your home is actually worth to rebuild — the millwork, the stone, the custom finishes — not a generic square-foot estimate that leaves you short in the one year it matters.
We walk the dwelling limit, the deductibles and the wind language with you line by line, then shop it across the markets we have access to.
What we look at
A home policy is only as good as these four pieces.
Dwelling & rebuild cost
Coverage to actually rebuild your home at today's construction costs — not just its market value.
Personal property & liability
What's covered inside the home, and protection if someone's hurt on your property.
Roof & construction
Roof age, roof type and how the home is built directly affect eligibility and price, especially in Florida.
Storm & water exposure
Wind and hurricane deductibles, and where flood is a separate policy you may still need.
Built for higher-value homes
The coverage details that matter above a certain price point.
Guaranteed & extended replacement cost
Options that keep rebuilding covered when construction costs come in above the estimate.
Scheduled coverage for valuables
Jewelry, art, watches and wine collections listed individually instead of capped by a blanket limit.
Umbrella liability
Liability limits layered above the home and auto policies, sized to what you actually have to protect.
Agreed-value for custom homes
For unique or custom construction where a standard replacement formula doesn't fit the house.
Availability of these options varies by provider, state and property. We'll tell you which ones your home actually qualifies for.
What to expect
Quotes are fast. Binding can depend on your roof.
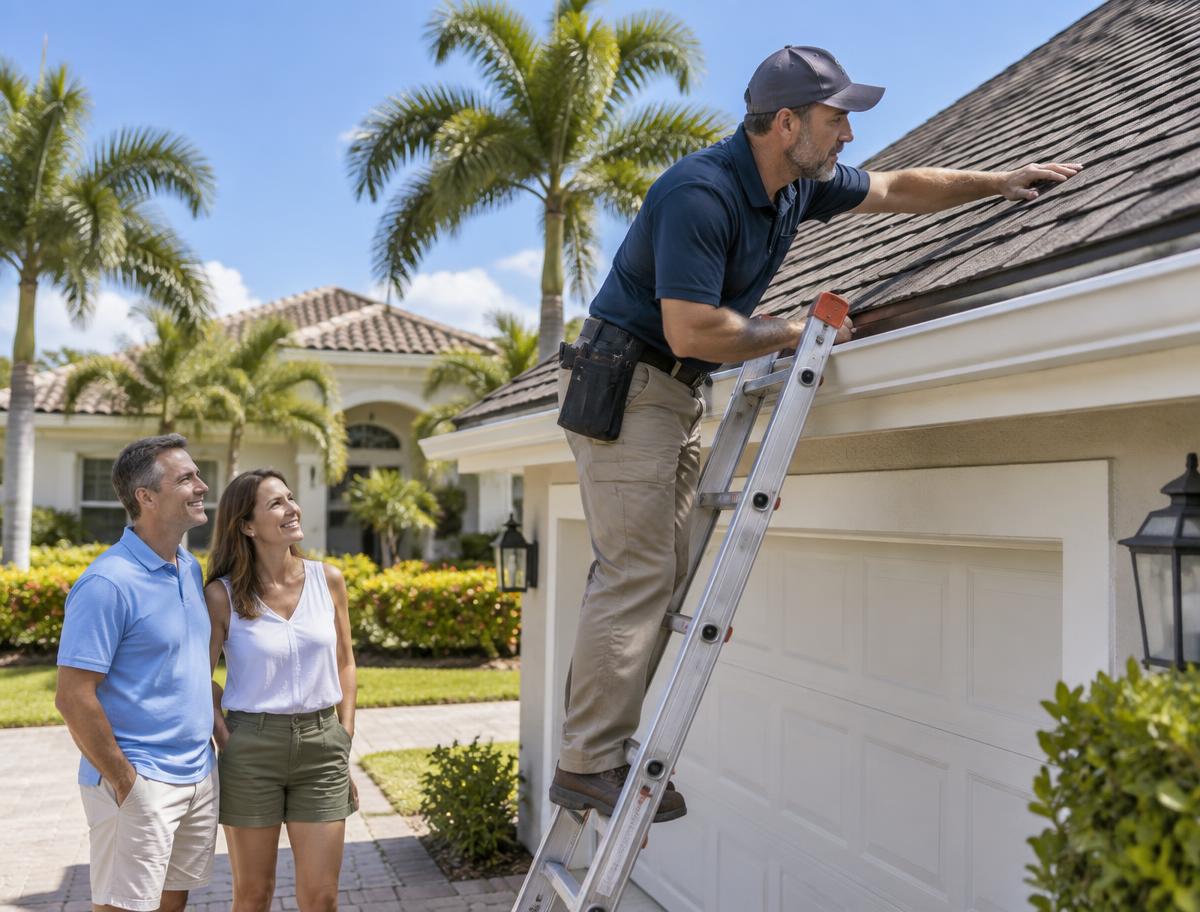
We can usually get you home quotes quickly. Putting the policy in force can depend on a roof or wind-mitigation inspection — especially for older homes in Florida.
If that's likely for your house, we'll say so up front. We'd rather tell you honestly than surprise you when a closing date is riding on it.
Timing
Good time to shop your home policy
Tell us the address and a little about the house. About a minute, no obligation.
Get Your Home Protected Properly- Your renewal jumped without a clear reason
- You just replaced your roof (can lower your rate)
- You're buying and need proof of insurance for closing
- Moving to Florida from another state
- Bundling home and auto to bring both premiums down
Add auto and quote both at once
Same conversation, two policies. Or call and we'll handle it on the phone.
Home coverage, eligibility and pricing vary by state, address, roof age and construction. Flood coverage is generally a separate policy. Replacement cost, scheduled valuables, umbrella and agreed-value options are subject to provider underwriting and are not available on every home. No savings outcome is guaranteed.